Hutchings England Pharmacy Market Update 2026

The Current Market
This England Pharmacy Market Update 2026 from Hutchings Consultants examines key indicators drawn from Hutchings’ data, including goodwill values, gross profit margins, buyer and seller trends, and the outlook for the market over the next 12 months.
Community pharmacy in England enters 2026/27 with renewed political commitment but continues to face significant operational pressures. The Community Pharmacy Contractual Framework (CPCF) funding settlement for 2026/27, announced in May 2026, totals £3.636 billion, an increase of £340 million compared with 2025/26 and one of the largest funding uplifts across the NHS. Although the additional funding does not fully address the sector’s funding gap or remove the underlying pressures associated with higher prescription volumes, rising employment costs, business rates, volatility in medicine supply and expanding service expectations, the improved settlement has nevertheless brought greater confidence and stability to the sales market.
Over the past 12 months, buyer demand observed by Hutchings has remained consistently strong across most categories, with potential purchasers frustrated by the limited number of quality opportunities reaching the open market. Buyers are increasingly focused on pharmacies that offer scope to develop clinical services, improve operational efficiency, and unlock additional profitability. Businesses with sustainable earnings and clear opportunities for future growth continue to attract the greatest interest.
The volatile government funding environment has led some corporate operators to continue reviewing their portfolios and, where appropriate, disposing of non-core branches as part of wider strategic reviews. Morrisons and Well Pharmacy have sought to reduce losses through branch rationalisation, as has Rowlands Pharmacy, which has moved away from certain retail locations as part of a pivot towards growth in hospital outpatient pharmacy operations. Consolidation also continues elsewhere in the market. Allied Pharmacies’ acquisition of a further 68 Jhoots pharmacies demonstrate how larger transactions can stabilise underperforming branches while extending an operator’s regional coverage.
Bank Funding
Pharmacy buyers continue to rely predominantly on bank finance, with only a small minority of transactions completing on a cash basis. The gradual reduction in the Bank of England base rate during 2025, from 4.50% to 3.75%, has provided a more stable backdrop for buyers and lenders than the peak-rate environment of recent years. However, lenders remain focused on sustainable profitability, service income, cash generation and the resilience of the underlying business.
Overall, banks already active in the sector remain positiveabout pharmacy acquisitions and continue to support them.
Sale timescales have remained relatively steady as transaction volumes have largely returned to normal following the exceptional period of large-scale corporate disposals in recent years. The market is therefore entering the next 12 months from a more stable position, with strong underlying buyer demand balanced against a limited supply of quality businesses.
Seller and Buyer Activity
Reflecting higher acquisition activity across the sector, the number of transactions completed through Hutchings has risen by 35% compared with 2025. This growth reflects sustained demand for profitable, well-located pharmacies, alongside a gradual improvement in buyer confidence and overall transaction activity. Corporate sellers disposing of non-core or superfluous branches have accounted for 47% of completions in 2026 to date, followed by group operators at 29% and independent owners at 24%.
The average turnover of pharmacies sold through Hutchings has continued to rise. Completed salesin 2026 to date have averaged £1,239,656, compared with £1,125,331 in 2025 and £902,173 in 2024. The average turnover of pharmacies for which sales have been agreed but have yet to complete is higher still, at £1,452,371, suggesting that larger businesses are increasingly coming to market. This trend may place some opportunities beyond the reach of many first-time buyers; a factor also reflected in Hutchings’ sales data.
As in the previous year, acquisition activity has been led by independent operators seeking to expand their existing businesses. Group operators and first-time buyers have accounted for the remaining purchases, highlighting continued demand from established pharmacy owners and new entrants alike.
Geographically, the Midlands and South West of England have recorded the highest levels of corporate and independent sales activity in 2026 to date, followed by the North East, North West and London. Regional variation remains evident, reflecting differences in the supply of pharmacies coming to market, local buyer demand, and the availability of suitable acquisition opportunities.
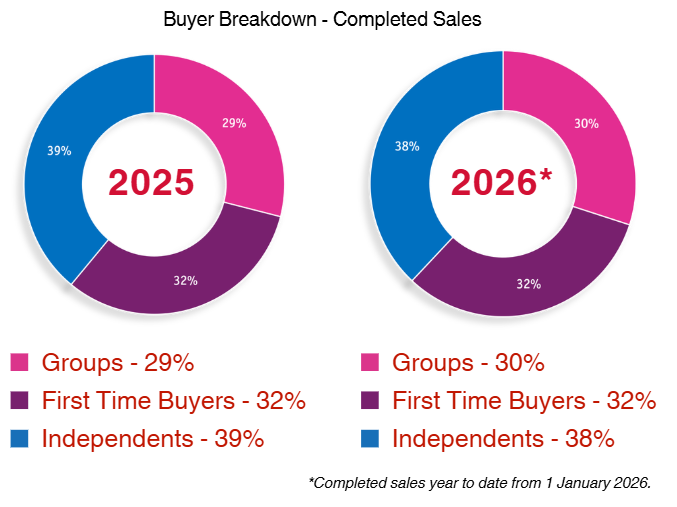
New buyer registrations have remained broadly in line with 2025, with activity weighted towards first-time buyers, who have accounted for 74% of registrations in 2026 to date. Independent owners represent a further 17%, with the remainder comprising group operators, previous owners who have sold, and investors.
While first-time buyers continue to account for most new registrations, registrations from group buyers have increased by 50% year on year. Their interest is primarily focused on corporate disposals, regional bolt-on opportunities and stronger independent pharmacies with clear potential to add value through services development, improved operational efficiency and growth in dispensing volumes.
Goodwill Values
The increased availability of corporate and multiple pharmacy opportunities in England during 2025 influenced goodwill values across both independent and corporate disposals last year. Independent pharmacies experienced some downward pressure as greater choice intensified competition for buyers’ attention, however on average, this segment achieved stronger pence-in-pound offers than many competing corporate disposals.
The corporate market remained mixed. Some high-performing, high-turnover branches achieved goodwill values above initial expectations, reflecting continued demand for strong businesses in attractive locations.
Since the beginning of Q1 in 2026, fewer pharmacies, particularly independent businesses, have come to market. Combined with an improving lending environment and greater certainty around government funding, this has strengthened buyer demand and contributed to higher goodwill offers in selected areas.
Hutchings’ data shows that current demand remains strongest for pharmacies in London and within the M25, with year-to-date goodwill offers ranging from £0.64 to £1.14 in the pound. The Midlands follows, with offers ranging from £0.59 to £0.98, while the North East has seen increased demand from independent owners expanding their portfolios and well-funded pharmacy groups, with offers ranging from £0.38 to £0.96 in 2026 to date.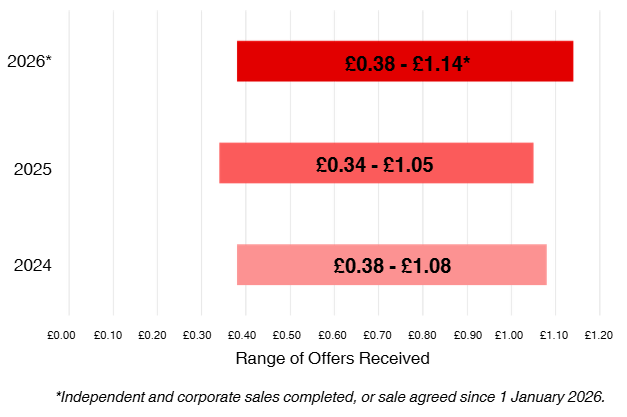
Average Number of Offers
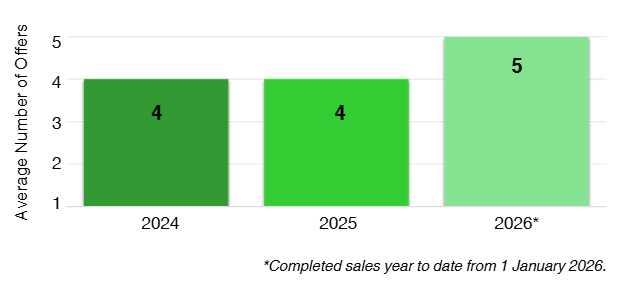
The growing proportion of profitable, higher-turnover pharmacies with stronger goodwill values coming to market has attracted interest from a broad range of buyers. This has been particularly evident among ambitious independent pharmacy owners seeking to expand and groups looking to make strategic additions to their portfolios.
Increased competition among buyers has, in turn, raised the average number of offers received per sale, although competition has varied between transactions and regions.
Gross Profit Margin
Ongoing challenges in the medicines supply chain continue to affect trading performance and profitability across the sector. Uncertainty over reimbursement, pricing concessions and the increasing time required to source medicines are placing further pressure on cash flow and operational capacity. For pharmacy owners, effective margin management has become increasingly important, not only to protect profitability and cash generation, but also to support business valuation, lender confidence, and buyer appetite.
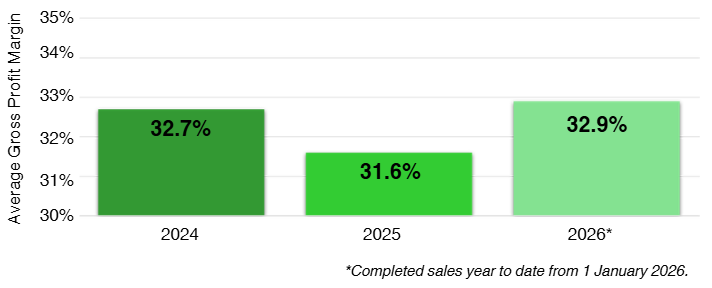
Hutchings completed transaction data for 2026 to date shows significant variation in gross profit margins across the pharmacies sold, ranging from 19.9% to 49.2%, with an average of 32.9% across England. This disparity highlights the importance of the underlying business mix and, in particular, the ability to generate income beyond core NHS dispensing. Pharmacies with a broader service offering generally achieve stronger gross profit margins than those that rely predominantly on dispensing income. In turn, stronger and more diverse income can support overall profitability and the potential goodwill value of the business.
Regional differences are also evident. London pharmacies continue to benefit from higher margins, with an average gross profit margin of 40.6%, followed by the South West of England at 35.4% and the North East at 33.0%. Profit margins in other regions are generally around 30%.
Market Outlook
The outlook for England’s pharmacy market over the next 12 months is cautiously encouraging. Greater certainty around government funding, improving lending conditions and sustained buyer demand are providing a more stable environment for pharmacy owners. Despite failing to fully meet the sector’s financial requirements, the 2026/27 CPCF settlement represents a significant increase in funding and, while challenges remain, it has helped to improve confidence across the sector.
At the same time, the limited supply of quality pharmacies is supporting competition among buyers. Well-performing businesses with sustainable profits, strong locations, and opportunities to develop additional services continue to attract interest from independent owners and pharmacy groups.
For pharmacy owners considering a sale in the coming months, current market conditions are supportive, particularly for businesses with strong underlying performance, diverse income streams, and clear opportunities for future growth. Notwithstanding a significant increase in borrowing costs, Hutchings anticipates continued firm buyer demand, together with the limited supply of quality pharmacies, to provide a supportive backdrop for growth in goodwill values over the year ahead.
If you are considering selling your pharmacy business, Hutchings Consultants Ltd would be pleased to have an initial, confidential discussion and provide a free verbal valuation.

Paul Steet
Associate Director
Tel: (01494) 722 224 (ext. 50)
DD: (01494) 422 850
MOB: 07478 344676
Email: paul@hutchingsconsultants.com
What our clients say about us…
“The main reason we chose Hutchings Consultants to manage the sales was a recommendation from a pharmacy colleague who had previously worked with Paul Steet when selling his own pharmacy a few years earlier.
I would confidently recommend Paul Steet to any pharmacy colleagues considering the sale of their business. My advice would be to engage with Paul as early as possible when thinking about selling or retiring, as there is a great deal of preparation involved in achieving a smooth transition and a less stressful process.”
Mr Daniel Wong
Greencross Pharmacy Ltd.